
Intermodal Transport
Rail and trucking combined under one strategy: operational continuity, visibility and control from start to finish.
When a container gets damaged in your custody, the carrier bills you at the carrier’s prices. This coverage exists so that bill never reaches your operation.
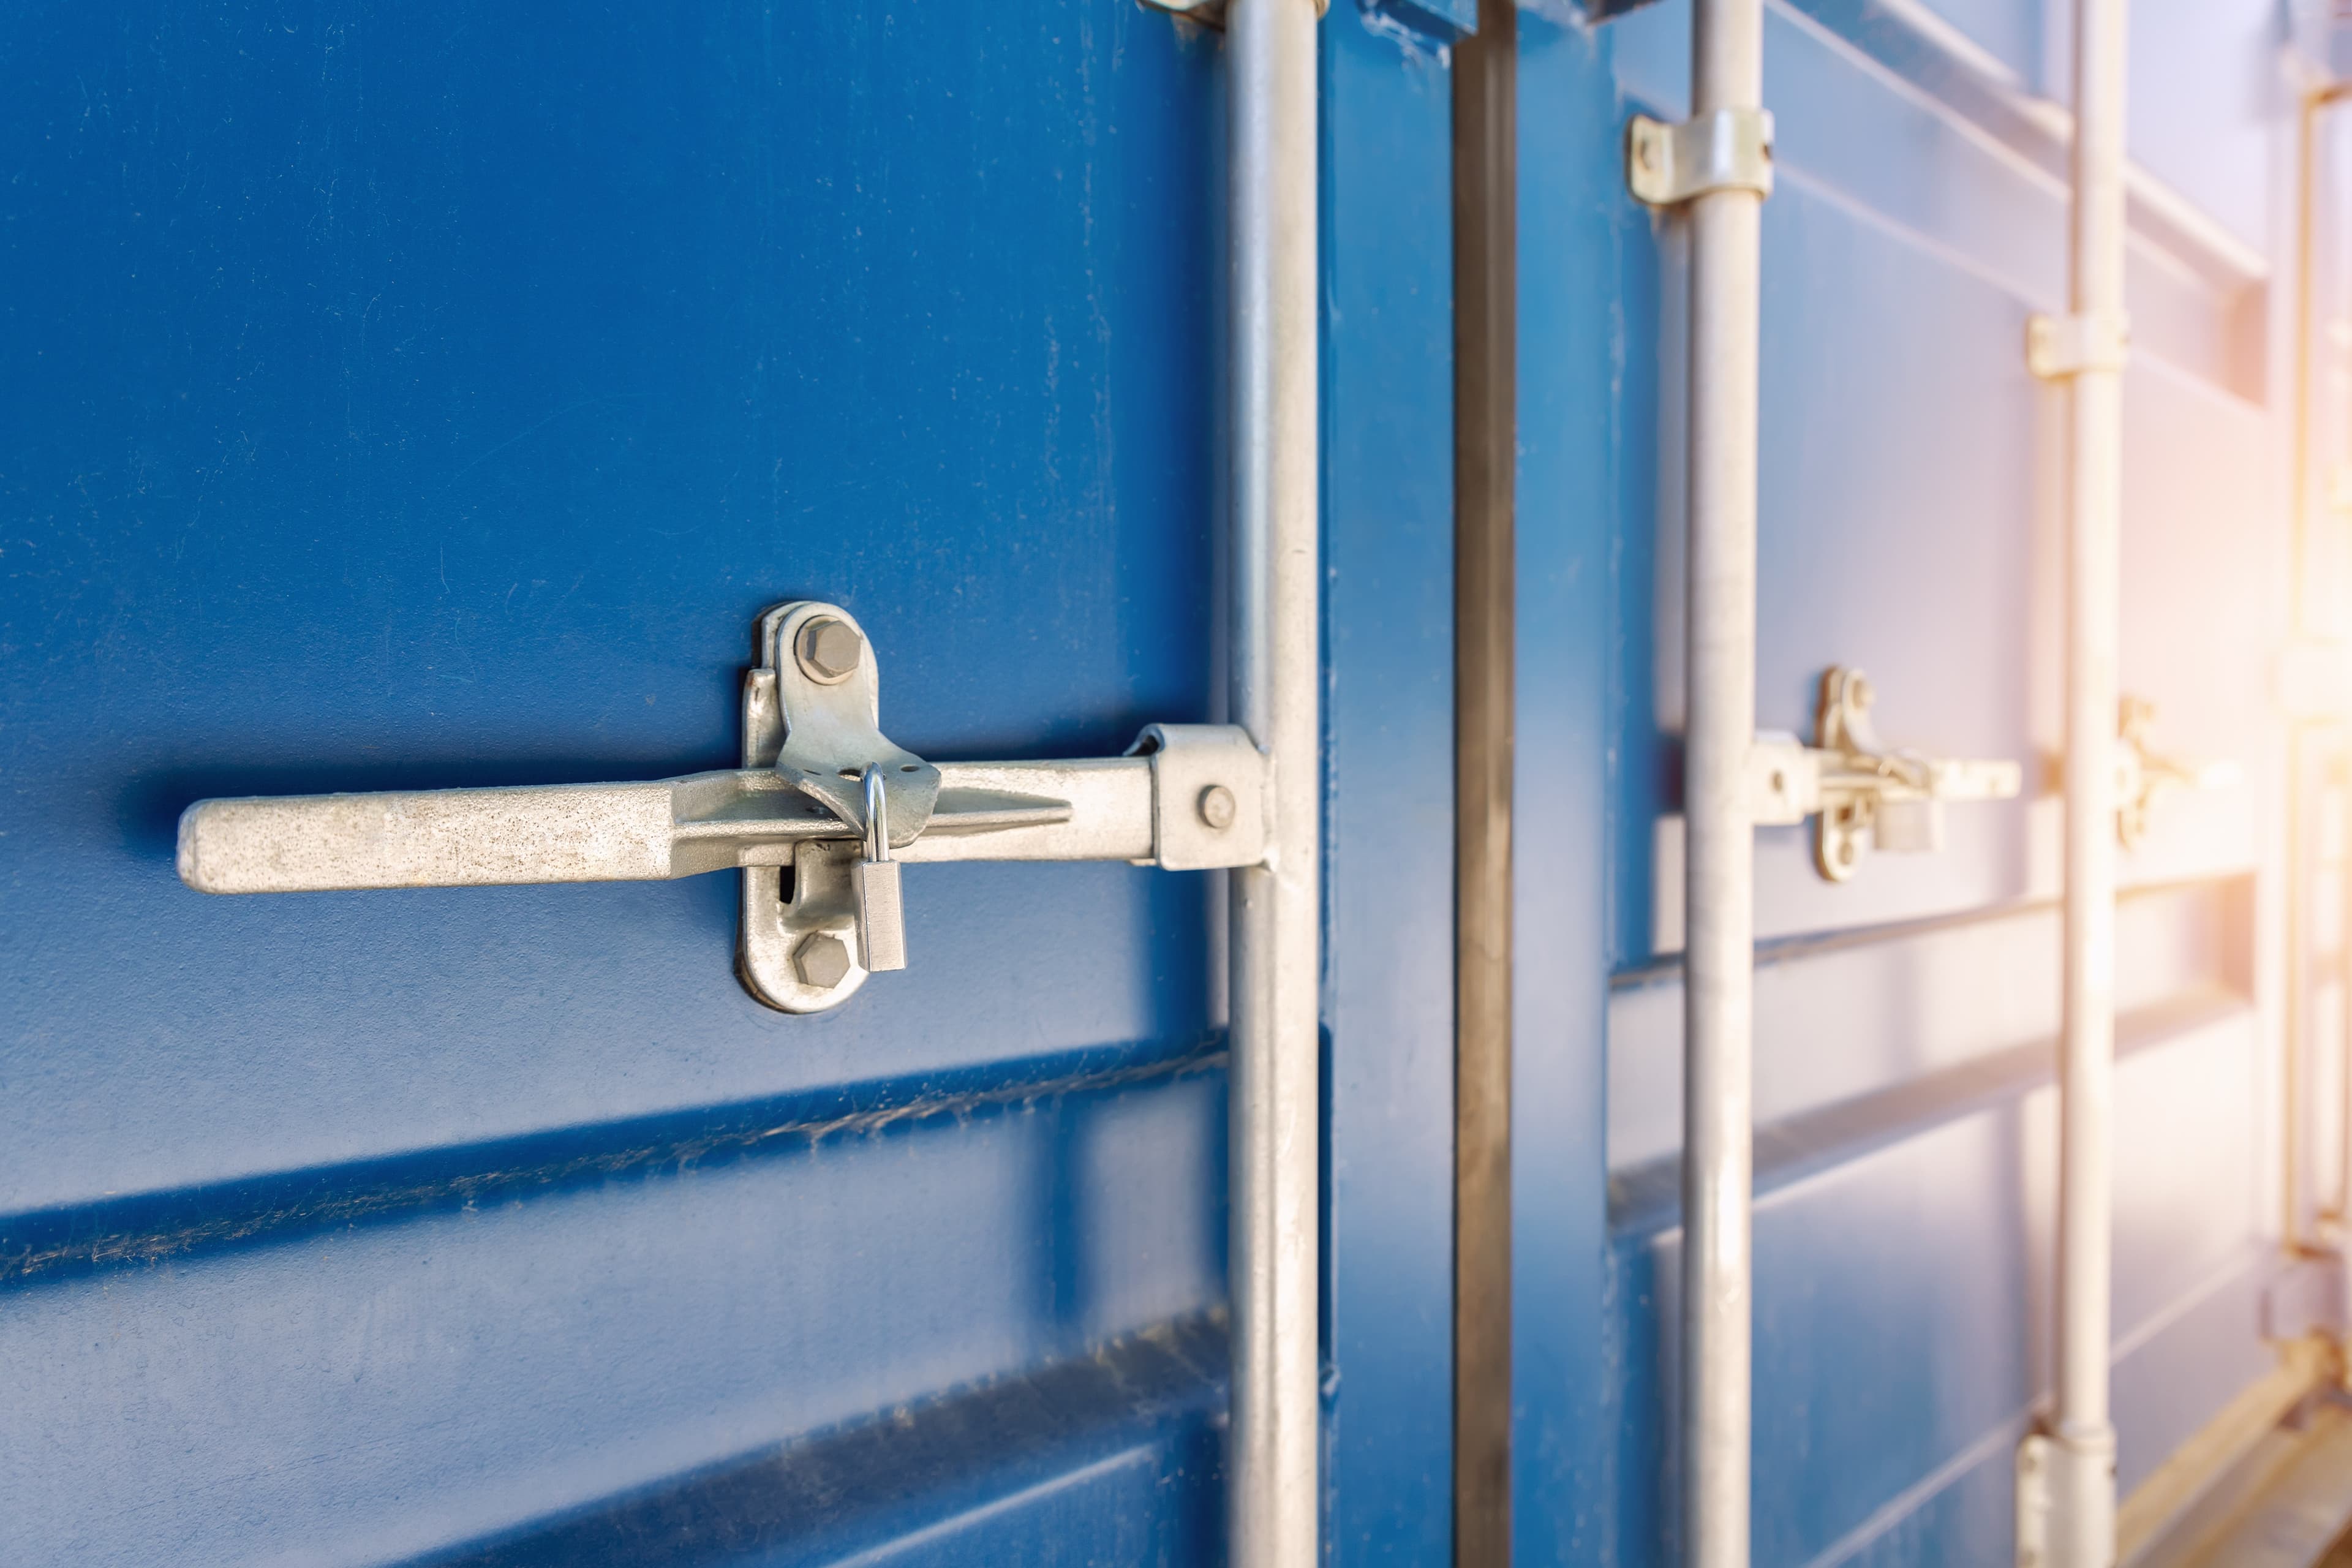
Few companies know this until it happens to them: from the moment you pick a container up at the terminal until you return it empty, the equipment travels under your responsibility. One knock during handling, damage in your yard or on the road, and the carrier invoices the repair — or the whole container — at rates you don’t get to negotiate.
Container insurance covers exactly that gap: damage to the equipment, loss, and liabilities arising from its use while in your custody. It’s the piece that complements cargo insurance — one protects what’s inside, this protects the box and your responsibility for it.
You move project or out-of-gauge cargo with complex loading and unloading
You use special equipment — flat rack, open top, reefer — where repairs cost multiples of standard
Your containers spend time in your own or third-party yards before going back
You’ve already received a carrier’s bill for equipment damage and don’t want a second one
Repair or replacement doesn’t come out of your cash flow: the policy absorbs it
Coverage built for the real gap: equipment custody from terminal to terminal
Complements cargo insurance — together they close the shipment’s full risk
Claims support included: survey, documentation and handling with the carrier
Container type, value, route and the handling involved — a standard dry box door to door is not a flat rack with project cargo.
Insured amount and scope matched to your actual operation, without paying for coverage your flow doesn’t need.
The policy is active before the equipment leaves the terminal — coverage bought after pickup is already too late.
If it does, we coordinate evidence, survey and the claim so the carrier’s bill doesn’t land on your account.
What you get
A policy active before the equipment moves, with coverage matched to your operation — and a team that manages the claim with you if it ever comes to that.
No. Cargo insurance protects what is inside. The container belongs to the carrier or a leasing company and sits outside that policy. If the equipment is damaged while in your custody, that bill arrives separately — even if your goods came through untouched. The two policies are complementary: one covers the cargo, the other covers the box and your liability for it.
Rail and trucking combined under one strategy: operational continuity, visibility and control from start to finish.
Accurate tariff classification for your imports and exports, under Mexico’s tariff schedule and the Harmonized System.
Quality inspections at origin to verify your goods meet spec before they ship.
Manage your international shipments with us. See how simple it can be.

